PROCESSING...

Anti-Money Laundering
Consulting Services & Strategies

0 Items - Total: $0.00 CAD

Who Wins The De-Risking Shell Game?

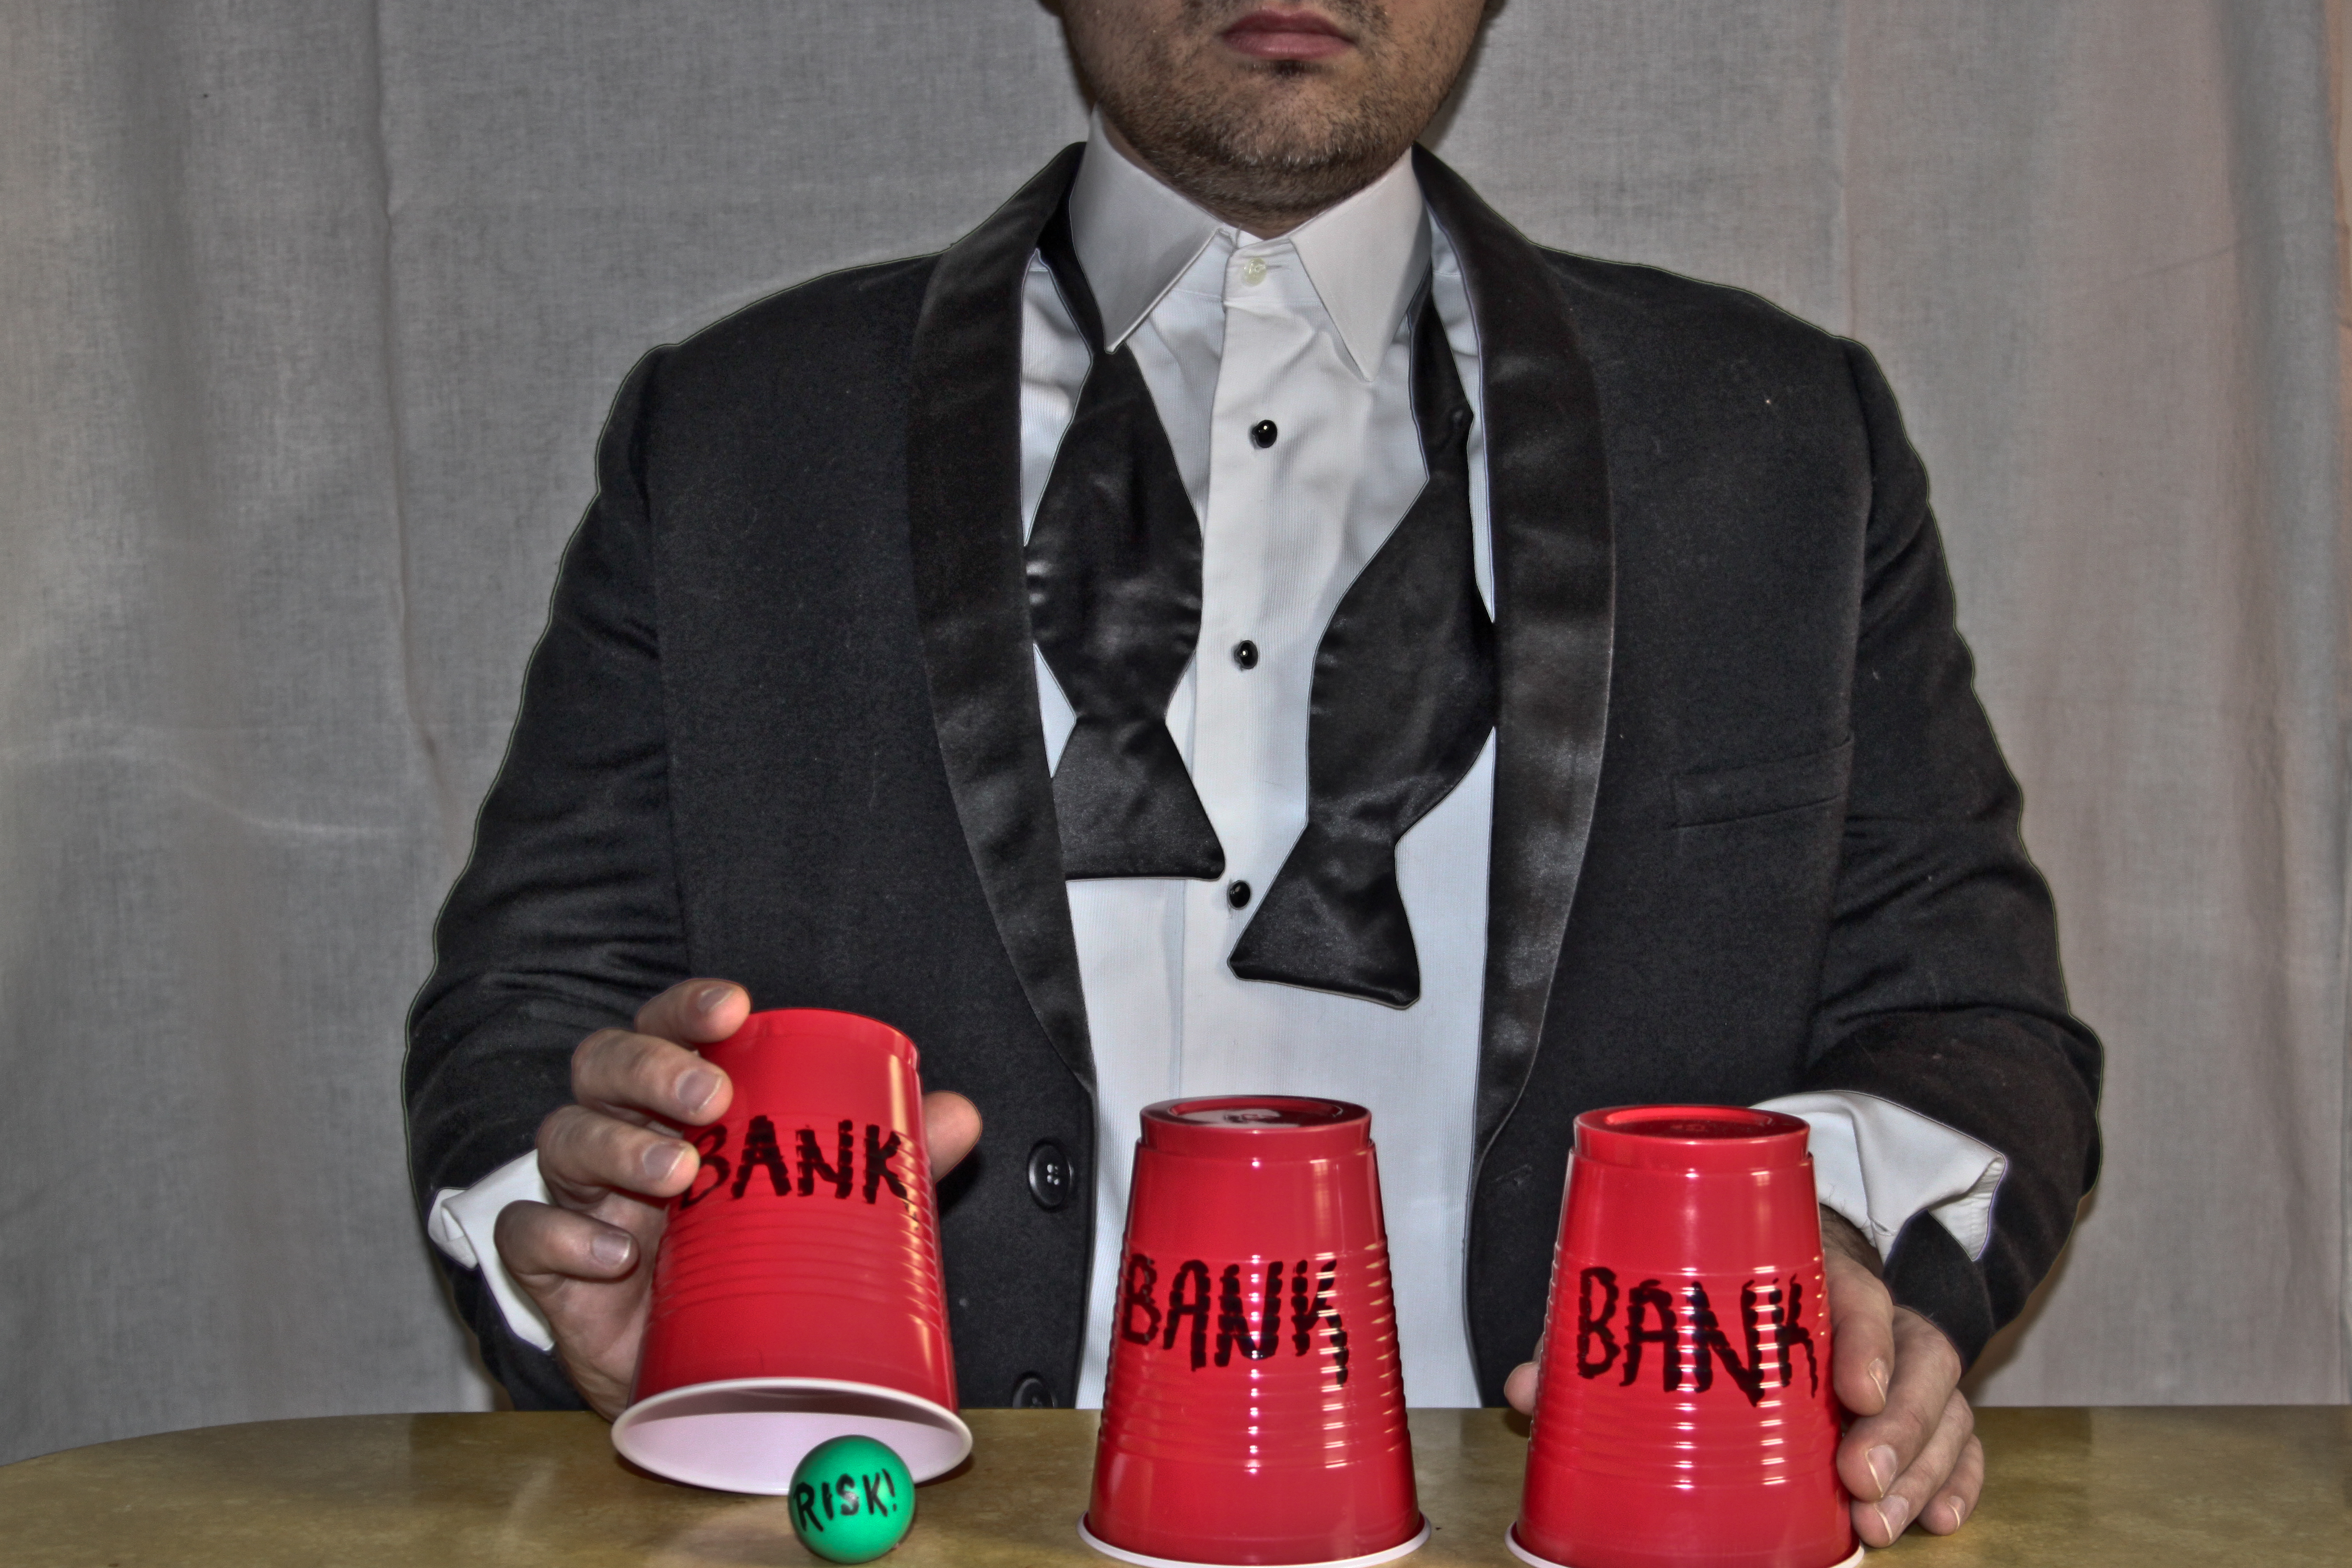
BankRisk_2The volume of evidence, both empirical and anecdotal, grows every day. The story on the surface is simple enough: banks are making the decision to “de-risk” (a polite way to say close the account of) certain types of businesses including money service businesses (MSBs) and digital currency businesses that are considered “too risky” by traditional financial services providers. The unintended consequences have included strained remittance corridors and frustration for businesses struggling to get by without reliable banking services. While these consequences are well documented, there are other unintended consequences of the de-risking phenomenon that have been less widely discussed. These include a growing lack of transparency between some industries and their banking service providers and directly threatens our ability to effectively manage money laundering and terrorist financing risk at both the financial institution and national levels.

It’s a shell game of “hide the risk” – and we’re all losing.

Businesses Are Losing

By now, if you haven’t heard about businesses struggling to survive without access to banking facilities, you would have had to ignore financial media for the past two years. The global effects of de-risking have attracted the attention of the G-20, the Financial Action Task Force (FATF), Financial Crimes Enforcement Network (FinCEN), the World Bank, and many more. While it’s clear that there are issues in terms of access to banking, let’s be honest with one another: while some businesses will close up shop, many others will take a different track.

Whether it’s using alternative financial service providers, payment processors, personal bank accounts or merely opening accounts at other financial institutions without revealing the true nature of the underlying activity, businesses will find a way to carry on. I’ve spoken personally to businesses that have taken these approaches, and it has never been their first or most ideal choice. These aren’t criminals carrying on some nefarious business! They are entrepreneurs who would rather be able to provide their real business plan to their banks and explain their activity honestly, but they do not believe that this option is open to them.

Banks Are Losing

Consequently, a bank with a policy that prohibits these types of businesses from holding accounts will deal with businesses that have gone to great lengths to conceal the true nature of their activity. The banks are unaware of the true nature of the activity passing through their accounts, and therefore ill equipped to manage the risk related to these activities. The strain on banking resources must be phenomenal, as banks must constantly devise new ways to interpret patterns of customer activity to detect undeclared MSB or digital currency activity. While it isn’t easy to quantify these costs, I can only surmise that the cost of this detective work must be high, despite being ineffective.

To further muddy the waters, businesses who fail to provide transparent information to their banks for fear of de-risking may also conduct completely legal activities in a way that starts to look like criminal activity. For example, if you believe that your business banking relationship is not reliable, you may open many accounts (in some combination of personal and business names) and conduct fractions of your banking through each, transferring funds from one account to another as needed to meet your obligations. On the surface, it can seem much like “layering” or “structuring” activity (techniques used by money launderers to make funds more difficult to trace). This further adds to the banks’ burden by creating more activity that must be monitored and investigated.

Entire Nations Are Losing

It has been widely publicized that in some cases like Somalia, entire nations that are dependent on remittance payments from friends and family living and working abroad are experiencing increased difficulty. Reliable and cost-effective remittance payment providers are a shrinking pool. This seems absurd in a time when technology can facilitate a payment in seconds.

National Security Is Losing

It’s not just far-flung places dependent on remittance payments that are losing. Here at home, we have a national security system that is dependent on our financial intelligence units (FIUs) having access to reliable data. The reliability of that data is undermined at every level by the de-risking shell game:

  • Businesses do not declare the true nature of their activity – and there are no incentives for them to do so;
  • Banks do not understand the nature of their customers’ activities, making it difficult detect potentially criminal activity; and
  • There is likely to be an increase in “false positives”, where activity conducted by businesses that do not believe that they can reveal the true nature of their activity to their banks instead conduct business in a manner that resembles criminal money laundering techniques.

Taken together, this results in the likelihood that key information is not being reported to FIUs correctly. Consequently, it becomes more difficult for law enforcement and other national securities to rely on this data to perform their roles effectively.

Who Is Winning?

There are two potential winners in this game and much like the shell games that you see duping tourists on the streets of large cities, neither is without malevolent intent.

The first are unregistered/unlicensed MSB businesses. These are businesses that have ignored regulatory requirements and carried on business without any FIU reporting. In some cases, these businesses will even minimize their interaction with the local financial system by using foreign bank accounts (and point of sale terminals) to collect customer funds. While the risk of penalty is high, the reward for these businesses (in particular where they are able to complete transactions that pose a challenge for their compliant counterparts) can also be high.

The second is criminal organizations. When legitimate businesses are performing transactions that look like money laundering, detecting true criminal activity becomes exponentially more difficult. I can only assume that the criminals are laughing all the way to the bank.

Shutting Down The Shell Game

De-risking is a complex problem with complex outcomes, but the solution need not be complicated. It does, however, involve the cooperation of all levels of the financial services community: regulators, banking service providers and businesses.

The costs and benefits of de-risking need to be reassessed. Where banking service providers are capable of accepting and managing accounts for businesses considered to be “higher risk”, they should do so, with their regulator’s blessing. Rather than perpetuating the shell game, regulators should encourage banking service providers to manage risk (and provide solid guidance with reference to how this should be done). Finally, there should be open communication between banking service providers, regulators and business banking customers. The lines of communication closed by de-risking must be opened, allowing banks to have honest conversations that will provide real insight into their customers’ business and lead to effective long-term risk management.
Insights From the 2014 CMSBA Conference

CMSBA

We were honoured to present at this year’s Canadian MSB Association (CMSBA) conference in Toronto. Speakers included representatives from the Financial Transactions and Reports Analysis Centre of Canada (FINTRAC), the Canadian Federation of Independent Businesses (CFIB), money service businesses (MSBs), consultants, lawyers and technology service providers. Priced between CAD 200 and 250 (depending on membership status and the timing of the registration), the price of this annual event, which includes breakfast, lunch, a post event reception, an annual CMSBA membership and a training certificate is likely one of the most informative and reasonably priced resources for MSBs. We would like to thank the CMSBA for providing a top quality event.

The Big Disclaimer

The information that follows is based on our experience attending the conference, and the information that we feel will help our friends and clients the most. While there were many excellent sessions, we weren’t able to enjoy them all. If you feel that we’ve missed something vital, or misrepresented an important point, please feel free to contact us and we’ll do our best to correct it.

FINTRAC Exams Are Changing

Lisa Douglas of FINTRAC tackled an update on the regulators expectations with candor, diplomacy and even a sense of humour on occasion. Among the most important points for reporting entities was the implementation of the regulatory changes that came into effect in February of 2014, and changes to the types of testing that FINTRAC will be performing in examination:

  • Business Relationships: has the nature and purpose of the business relationship been documented? Has the customer been identified where there is a business relationship (and if not, are efforts to identify the customer documented)? Is ongoing monitoring in place?
  • Suspicious Activity: Do the policies and procedures reflect the right indicators for the business model (see FINTRAC’s Guideline 2 for a full list)? Is there activity that seems to be suspicious that was not reported? If so, are you able to explain objectively why the activity was not considered to be suspicious (and is the explanation backed up by documentation)?
  • Ongoing Monitoring: Are monitoring efforts documented? Is the monitoring for high-risk customers and business relationships different (in nature and frequency)?
  • Beneficial Ownership: Is there documentation that confirms beneficial ownership? If not, has Senior Officer been identified and is the customer classified as high risk?
  • Customer Information Updates: Is customer information being updated on a regular schedule according to the customer’s risk?
  • Quality Reporting: Are the reports that FINTRAC receives complete and accurate? Are all fields (including fields that aren’t mandatory) completed if you have the information on file?

Ms. Douglas received the most questions about applying an ‘objective standard’ to deciding whether or not there are reasonable grounds to suspect money laundering or terrorist financing activity, and stressed that it is not enough to know that the activity is consistent for a customer over time if the activity could be indicative of money laundering or terrorist financing. This theme was echoed by Paul Burak of MNP LLP in his discussion of customer due diligence. In his illustrative example, Mr. Burak described a hotel that made large cash deposits with few credit card or debit card payments, in volumes that were out of synch with local tourist traffic. While the pattern of activity was consistent for the client over time, it did not make sense when an objective standard was applied.

There are Many More MSBs with ‘Zero Deficiencies’ Than MSBs with Penalties

Although there are several published administrative monetary penalties that have been published for MSBs, approximately 25% of MSBs examined between 2008 and 2014 have passed examinations with zero deficiencies.   While this isn’t likely to reduce the stress that comes with preparing for an examination, the information (obtained from a recent access to information request that Outlier filed with FINTRAC) is important in understanding that the MSB industry has historically been more compliant than the headlines would have us believe. That said it’s always vital to take the time to prepare for your examination and ensure that all of the materials requested by FINTRAC are assembled and delivered on time. We’ve put together some free resources to help reporting entities get organized, available here.

We were fortunate enough to co-present on this topic with two very experienced lawyers, J. Bruce McMeekin and Tushar K. Pain. Both emphasized the importance of reaching out to a legal professional early if you may be facing an administrative monetary penalty, as well as the value of regular compliance testing (not just limited to the effectiveness reviews required every two years) to assess compliance and fix anything that may be offside.

Banking Remains an Issue for MSBs

Robert Osbourne of Grant & Thornton provided excellent insights on maintaining banking relationships, including requesting and account manager, and maintaining regular contact (rather than simply responding to issues or information requests). Despite recent public policy positions from the Financial Action Task Force (FATF) and Financial Crimes Enforcement Network (FinCEN) warning against wholesale de-risking, few Canadian banks are currently accepting MSBs. Among those that we are aware are taking on MSB customers:

  • Royal Bank of Canada (RBC)
  • Bank of Montreal (BMO)
  • DirectCash Bank (DC)

There are additional financial institutions, including credit unions that offer accounts to MSBs, however many of these are not currently taking on new MSB customers. Access to banking is one of the issues that we’re likely to hear more about from both the CMSBA and the CFIB in the coming months.

Tools and Technology

The importance of tools and technology for recordkeeping and compliance management cannot be understated. The Canadian market is served by a number of great providers, and more solutions are being added on a regular basis. The solutions that are implemented should be well aligned with your business model and Risk Assessment. They should also be secure, in particular where sensitive or personal information (PI) is stored. Garry Clement of Clement Advisory Group emphasized how vulnerable the industry may be to cyber threats, and steps that MSBs can take to recognize threats and protect their data.

Digital Currency

Jillian Friedman of the Bitcoin Embassy (formerly, now she can be found at montrealtechlawyer.com) and Susan Han of Miller Thompson provided an overview of digital currency. While it was clear that many MSBs are interested in the potential that bitcoin and other digital currencies can offer, the same barriers to banking faced by MSBs are faced by digital currency companies in Canada. MSBs that deal in digital currency may face additional de-risking concerns with their banks. Zach Ramsay of CoinCulture, though not presenting, was on hand to offer clarification about the digital currency related services that may interest MSBs including bitcoin teller machines (BTMs) and bitcoin payment processing.

Need a Hand?

If you would like more information about the CMSA, including information about how to become a member, you can contact them here.

If you have questions about AML or ATF compliance, please contact us for more information.

Why We Believe In The Right To Business Banking

I remember my first thoughts on money services businesses (MSBs) very distinctly.   Years ago, when I moved from being a banker to being a consultant, I thought of MSBs as being predatory and fly by night. I didn’t know much about MSBs, and I was hesitant to work with them as clients. Fortunately, a colleague determined to change my point of view, brought me to a meeting with one of her clients, a remittance company that served a particular ethnic community.

My colleague asked her client to walk me through the business model, and as the discussion progressed, I quickly understood that the MSB was offering many services that the banks were not – some of them free of charge. Not only was the MSB providing services in their customers’ native language, the fees were low and there were a slew of additional services like lawyer and employment agency referrals (all services in the customers’ native language). The office space was a bright and clean retail location and all of the staff seemed genuinely excited to be there. It was clear that I had misjudged MSBs (or at the very least, this MSB).

Over the years I’ve worked with many MSB clients and have come to understand that this was not a unique situation. In Canada we have many great MSBs that are providing services in nimble and efficient ways that truly meet the needs of their communities. My team and I have been able to help MSBs build compliance programs, risk assessments, training and complete effectiveness reviews, but the most common request that we’ve received is something that we’re simply not able to do: open a bank account.

From startups to MSB businesses that have been in existence for many years, opening a bank account (and keeping it open) is more difficult than staying in compliance with the law, or running a profitable business. Recently, we’ve also been approached by companies that deal in digital currencies like bitcoin with the same type of request. While we can certainly provide advice on how to approach the problem (see our blog on keeping your bank happy), we aren’t a bank and don’t have the power to compel banks to open accounts for our customers, or to keep them open. The lack of available banking facilities is deeply troubling to me, both as a Canadian entrepreneur and as a compliance expert.

Stifling Innovation

Recently, the Canadian Senate Committee on Banking, Trade and Commerce held sessions related to digital currency. One of the messages that was clear in all sessions was the disconnect between the traditional financial system (represented primarily by banks) and the emerging digital currency markets. While digital currency has come a long way, companies have difficulty operating using digital currency alone. Unfortunately, many of these companies are currently unbanked (including companies that have a history of profitability and companies that accept payment in digital currency – but do not sell digital currency to the public). While Canada is, in many ways, recognized as a hotbed of digital currency innovation, banking challenges are daunting to companies considering a Canadian presence.

While some laud the regulation of digital currencies expected to come into play following the Royal Assent of Bill C-31 earlier this year, it is noteworthy that this is unlikely to solve the existing banking issues faced by these companies. ‘Dealers in digital currency’ (a term that has yet to be fully defined) will be regulated as MSBs, and MSBs face very similar banking challenges despite being regulated entities. New MSB startups (including MSBs that aren’t dealing in digital currency) have great difficulty in obtaining and maintaining basic banking facilities.

The Risk of ‘De-Risking’

As an entrepreneur, it troubles me that companies that have followed all of the rules are denied the opportunity to innovate because they don’t have access to banking services. As a compliance professional, I’m equally troubled by the workarounds that I’ve seen in action. These have ranged from misrepresenting the nature of a company’s business to incorporating multiple companies that settle transactions between one another (or access banking services on one another’s behalf) to the use of personal bank accounts to operate businesses. In essence, accessing banking in a way that banking service providers don’t understand because providing accurate information is seen as putting the business at risk.

Banks and other banking service providers are heavily regulated, and their requirements include knowing their customers and understanding their customers’ transactions. MSBs and digital currency businesses are generally (effectively always) seen as being higher risk and requiring enhanced due diligence (EDD). There are few motivations for banking service providers to take on higher risk customers, in particular if the banking service provider cannot be certain that the account will be profitable. To this end, some banks have openly stated that they will not deal with MSBs or digital currency companies at all. Others charge screening fees (which can range up to several thousand dollars) required as part of the account application process, with no guarantee of an account. Most banks that offer accounts to these types of businesses charge fees (in addition to regular banking fees) in order to maintain accounts.

Even when an MSB or digital currency company opens a bank account, there is the possibility that the banking service provider will close the account (referred to in the banking community as “de-marketing” or “de-risking”) with very little notice. Consequently, there is very little incentive for MSBs or digital currency companies to be transparent with their banking service providers. These businesses need bank accounts in order to thrive, and they don’t perceive themselves as being able to access banking services by being open and transparent. This creates a situation wherein many companies operate “under the radar,” accessing banking services without providing a fulsome understanding of their business or transactions.

In these situations, banking service providers are not meeting their regulatory obligations as they don’t truly know their customer, nor understand their transactions. Many financial institutions have mechanisms in place to detect undeclared MSB activity and /or digital currency related activity. While it’s not possible to say with certainty how effective these controls are, my experience would suggest that the number of financial institutions that are dealing with MSBs and digital currency businesses is close to 100% (regardless of the policies or controls in place). In other words, de-risking MSBs today is about as effective as the prohibition of alcohol in the USA in the 1920s…

Not Just A Canadian Issue

Businesses across the globe are facing similar issues, and international groups such as the World Bank have become more vocal in proposing solutions.  In their 2013 Special-Purpose Note titled “Barriers to Access to Payment Systems in Sending Countries and Proposed Solutions,” the World Bank’s  Global Remittances Working Group (GRWG) suggest five solutions, including the creation of banks focussed on serving money transfer businesses.  The issue was raised again during Global Payments Week in New York, where it was noted that it has been brought to the attention of the G20 Ministers of Finance.  While the issue is not uniquely Canadian, we believe that Canada could become a world leader in implementing a solution.

Solving The Problem

We believe that the solution to mitigating the risk related to MSB and digital currency transactions is not de-risking. This strategy only penalizes honest companies and creates an environment of mistrust. We believe that all Canadian businesses should have a right to basic banking services, in the same way that individuals are entitled to these services. In order for this to be true, businesses would need to be included in the rules set out in the Access to Basic Banking Services Regulations under the Bank Act, or similar legislation.

The risk posed by MSBs and digital currency businesses should be assessed and managed. This can only occur where these companies understand that revealing the nature of their business will not lead to “de-risking,” provided that the business is operating within the parameters set out by Canadian law (including the requirement for MSBs to be registered with FINTRAC in Canada and licensed by the AMF in Quebec). While the cost of managing related risks and performing enhanced due diligence exist, the fees related to MSB and digital currency accounts should not be so unreasonably high as to prevent access for smaller companies.

We’re Not Lobbyists, But…

Canada’s 2014 Economic Action Plan mentions “universal banking.” The website reads: “Universal access to basic banking is a cornerstone of Canada’s financial sector in which Canadians can take pride.” We’re working with industry groups to spread the message. We believe that universal banking should apply not only to individuals, but to the Canadian organizations that are innovating and helping to make Canada great.

What You Can Do

If you believe in the right to business banking, as we do, we encourage you to contact your Member of Parliament to share your thoughts.

If you own a business in Canada, you can also contact the Canadian Federation of Independent Businesses (CFIB) to request action on this initiative.  CFIB has been a powerful lobbying force for Canadian businesses in the past, and we have discussed these issues with them.  Action is most likely when it is clearly supported by their membership.

MSBs and those that work with MSBs may also consider contacting the Canadian MSB Association (CMSBA) to learn about their current initiatives.  The CMSBA represents the interests of Canadian MSBs, in addition to providing training and conferences (the next of which takes place November 18th in Toronto).

Contact Us

You can contact Outlier at any time using our online form or contact the author directly by emailing amber@outliercompliance.com.

Keeping Your Bank Happy

For many reporting entities, a growing concern has become obtaining and maintaining banking relationships.  Most, if not all, businesses need a banking relationship to survive and prosper.  If you are an individual in Canada, you are entitled to basic banking services, but it is not so for businesses.  Banks and other financial service providers choose the business customers that they will serve.  This means that the stakes can be very high for businesses shopping for a banking relationship.

As reporting entities themselves, banks and other financial services companies have similar obligations to other reporting entities.  They must understand their customers and their customer’s transactions.  There is mounting pressure for banks to conduct due diligence that includes reviewing the compliance programs of clients that are reporting entities.  As a business owner, your best defence against losing your banking relationship is making your banker’s work easier.

This isn’t something that most business owners have spent a lot of time thinking about, but a few hours every year can go a long way towards ensuring that your banking relationships keep operating smoothly.  Based on my clients (and my own) experiences, I’ve summed up a five-step plan to help you on your way, which includes links to free resources to help you get started.

Step 1:  Have A Compliance Program (and Keep It Up To Date)

All reporting entities need to have an anti money laundering (AML) and anti-terrorist financing (ATF) compliance program in place, that includes these five elements:

  1. Appoint A Compliance Officer (this is the person that is responsible for the compliance program; they should be fairly senior within your company and their appointment should be documented);
  2. Document Your Policies And Procedures (your documentation should be detailed enough to describe what you actually do, and be updated at least once a year);
  3. Create A Risk Assessment (this is a document that describes the risk that your business could be used to launder money or finance terrorism, and the controls that you have in place to prevent that from happening);
  4. Train Your Staff (this should happen at least once a year and all training sessions should be documented); and
  5. Have An AML Compliance Effectiveness Review (this is like an audit of your AML program and operations; it must be done at least every two years).

When you are creating and updating your documentation, remember that you and your staff are not the only people that will see it.  Your regulators, bankers and other people that don’t know your business the way that you do will also need to rely on your documentation.  This means that you need to write as if your reader doesn’t know your business.  Take the time to explain everything clearly.

If you need help creating a compliance program, please have a look at our resources pages for your reporting entity type or contact us.

Step 2:  Have a business plan

Your business plan should describe what you do, how you make money and include historical business volumes (for existing businesses) and predicted business volumes (for new and existing businesses).  This document should explain your business simply and clearly (to someone outside of your industry).  To make things easier for your banking service provider, you should explain the types of transactions that will go through your bank account and the estimated volumes.

Many business owners are hesitant to describe their transactions and marketing strategies in any type of document that will leave their hands.  This type of thinking can seriously harm banking relationships, especially if the bank perceives you as being secretive or evasive.  Remember that the bank needs to understand your business in order to keep you as a customer, and the easier that you can make it for them to understand, the better off you’ll be.

I’ve worked with consulting firms that charge high rates for business planning, but there is no real need to spend a lot of money creating a business plan.  There are many free resources available for Canadian businesses.  Here are some of my favourites:

Not surprisingly, the banks themselves offer many of these resources!

Step 3:  Have Contracts In Place

Any third party that is involved in your business (vendors, agents, etc) should have contracts in place, and your bankers may ask to see these agreements.  The contracts should spell out what the third party is obligated to do on your behalf and the copies of the agreements that you provide to your banker should be signed and dated by all parties.  Don’t provide original documents to your bank unless you are required to do so (often banks want copies only, as they will not be returned to you).

Many existing businesses have long-term business relationships that may never have had a formal agreement in place.  In these cases, especially if the third party is doing something like identifying customers on your behalf, you will need to get written agreements.  These don’t need to be overly complicated.  The agreement should state what all parties are required to do and when.  It can be a plain language document that you draft yourself, or something more complicated that you work on with the advice of a lawyer.  The important thing is that you have agreements in place and that they’re clear enough to allow the reader to understand how the parties are related.

Step 4:  Take The Time to Build Alliances

You don’t usually get to speak directly with your bank’s compliance department. The sales representative or branch manager is your liaison. They need to be your advocate.  In this type of scenario, a person becomes your advocate not because you’re cute or gave a nice gift but because they know, understand and can explain your business. This takes patience and time.  Remember you need them as much as they need you. Make it a no brainer for them to want you as a customer (profitable, low risk, low effort).

Your representative at the branch is your point of contact and can act as a sounding board for your documentation.  For instance, if they have requested your business plan, ask if you can walk through it with them and get their advice before it is submitted to the bank’s head office or compliance department.  Remember that they can’t write documentation for you, but they can provide excellent insights about what the bank expects to see.

Step 5:  Consider Having Audited Financial Statements Completed

In some cases, your financial service provider may require audited financial statements. Only a licensed accounting professional or firm (specifically someone with a CA or CPA) can issue this type of report in Canada.  The process involves an independent evaluation of your company’s financial statements and other documents.  The auditor expresses an opinion about your company’s financial statements, based on the audit work performed, to state if they feel that the financials are free from material errors.  This is not specific to anti-money laundering.  The audit report refers to the company’s financial risk and fraud risk, among many other topics, to give your financial service provider more comfort over the financials they are reviewing to help lower your risk profile.  While we at Outlier aren’t accountants, and don’t perform this type of work, we’re happy to recommend accounting firms that have experience with audited financial statements, including our friends at Helen Loukatos Chartered Accountant, who’ve generously given us permission to link to this Money Service Businesses Audit FAQ.

Stepping It Up

All of this is relatively simple, but it takes time.  Consider it an investment in your business.  If you need a hand getting started, please feel free to contact us.

Return to Blog Listing